Borrowing Capacity and Affordability Are Not the Same Thing
Getting approved for a large home loan can feel like good news.
You speak to a lender or mortgage broker, provide your income and expenses, and eventually hear the number you have been waiting for:
“You could potentially borrow up to $900,000.”
For many buyers, that number immediately becomes their property budget. A $900,000 borrowing capacity plus their deposit might suddenly mean looking at properties around $1 million or more.
But there is another question that deserves just as much attention:
Just because a lender may be prepared to lend you $900,000, should you actually borrow $900,000?
They are two different questions.
A lender's borrowing capacity calculation is designed to assess whether your application meets its credit and servicing requirements.
It considers things such as your income, debts, living expenses, dependants, credit limits, loan term and other financial commitments. The lender then applies its own servicing methodology and credit policy.
What that calculation cannot fully understand is the life you intend to live after buying the property.
It doesn't know whether you want another child in two years, whether one partner plans to reduce working hours, whether you want to continue travelling, pay school fees, build an investment portfolio, help family financially or simply maintain a comfortable amount of money left over each month.
That is where borrowing capacity and affordability begin to separate.
At Triple O Finance, we believe buyers should understand both before deciding how much they are comfortable spending on a property.
Key Takeaway
Your maximum home loan borrowing capacity tells you what may be possible under lender policy. It does not automatically tell you what level of mortgage will comfortably fit your lifestyle.
Borrowing Capacity Is Not The Same As Affordability
Borrowing capacity estimates how much a lender may be prepared to lend based on its credit policy. Affordability is a much more personal question.
It asks:
Can I make these repayments while still living the life I want to live?
That distinction matters.
It matters because lenders assess an application using income, existing debts, living expenses, dependants, credit limits, loan terms and other commitments. They also apply their own servicing assumptions.
Australia's prudential regulator, APRA, currently requires regulated banks to assess new housing borrowers using a mortgage serviceability buffer of at least three percentage points above the applicable loan rate.
That buffer matters because it provides extra protection if interest rates rise or a borrower's financial circumstances deteriorate.
But it still doesn't create your household budget for you. A bank may conclude that you satisfy its lending criteria. That doesn't necessarily mean borrowing to the maximum will leave enough room for everything else that matters to you.
A Better Question
Don't stop at “How much can I borrow?” Ask “How much can I comfortably repay while still achieving the other things that matter to me?”
What Does A $900,000 Mortgage Actually Look Like?
Large numbers can feel abstract until you convert them into monthly cash flow.
Using a 30-year principal-and-interest home loan as an example, a $900,000 mortgage at 6.15% would require repayments of approximately $5,483 per month.
That is roughly $65,800 per year in mortgage repayments.
Now consider what happens if the interest rate were two percentage points higher.
At 8.15%, the same $900,000 mortgage would require repayments of approximately $6,698 per month. That is around $1,215 more every month, or roughly $14,580 more each year.
| Loan Amount | Approx. Repayment at 6.15% | Approx. Repayment at 8.15% |
|---|---|---|
| $700,000 | $4,265/month | $5,210/month |
| $800,000 | $4,874/month | $5,954/month |
| $900,000 | $5,483/month | $6,698/month |
Illustrative repayment examples only. Calculations assume a 30-year principal-and-interest term and exclude fees. Actual repayments depend on your loan, rate and lender.
This is not a prediction that rates will rise by two percentage points. It is a household stress test.
Moneysmart recommends borrowers consider what repayments would look like if interest rates increased by around two percentage points. It is useful because it changes the conversation from what you can afford today to what your household could absorb if circumstances changed.
Higher interest rates aren't the only change worth testing.
Ask what would happen if one income temporarily reduced. Could you continue making the repayments for three months? Six months?
Then consider where additional mortgage costs would come from. If repayments were $500 or $1,000 higher each month, would you reduce investing, holidays or discretionary spending? Would you need to use savings?
The purpose isn't to predict exactly what will happen. It is to understand how much flexibility exists in the household before taking on the debt.
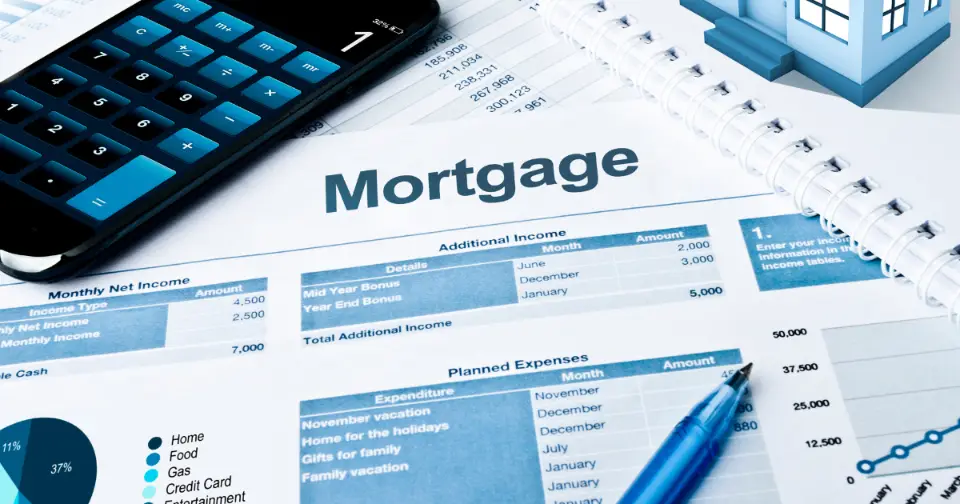
The Bank Does Not Know Your Five-Year Plan
Imagine a professional couple earning a combined $220,000 per year. They have stable employment, limited consumer debt and a solid deposit. After assessment, they discover they may be able to borrow around $900,000.
On paper, buying near the top of their range may be possible.
But their plans tell us something the borrowing calculator doesn't.
Within the next three years they would like to have their first child. One partner may take parental leave and later return to work three days per week. They also want to continue investing $1,000 per month and take an overseas holiday every second year.
Their lender's servicing calculator cannot fully understand the emotional or lifestyle importance of those plans.
The Lender Asks
Can this household service the proposed debt according to our policy?
The Household Should Ask
Will this debt still allow us to live the way we want to live?
This is why it can be useful to think about two limits:
Your lender maximum - What may be available under lender policy.
Your personal maximum - What you are comfortable borrowing after considering the life you expect to live.
Your personal maximum should look beyond today's bills. Think about where your household may be three, five or even ten years from now.
Could you have children?
Could one income reduce temporarily?
Will school or childcare costs become relevant?
Do you expect to upgrade cars?
Would you like to continue investing?
Do you financially support parents or other family members?
Do you want to travel?
Could you comfortably manage a period between jobs?
None of those questions automatically means you should borrow less. They simply belong in the decision.
In our example, the couple might conclude that $750,000 or $800,000 of debt better fits their plans, despite potentially having access to more. That isn't failing to maximise their borrowing capacity. It is choosing how much financial flexibility they want to preserve.
Why Borrowing Power Can Differ Between Lenders
Another important consideration is that borrowing capacity itself is not necessarily one fixed number.
Online borrowing power calculators can be useful for getting a rough estimate, but they should not be treated as an approval or a final property budget.
Lending is not based on one universal calculator.
Different lenders can assess the same household differently because their policies may treat income, expenses and existing commitments differently.
This becomes particularly important when your income isn't simply a fixed base salary.
A nurse may receive shift penalties and overtime. A police officer may receive allowances, loading, overtime or higher duties. A medical professional may have several income sources. A self-employed borrower may require an entirely different income assessment.
One lender may recognise more of a particular income source than another. Another may assess an existing liability differently.
This is why an estimate from your existing bank does not necessarily represent your position across the broader lending market. It may be completely accurate under that bank's policy while another lender reaches a different result.
But there is an important distinction:
The objective isn't to find the lender willing to lend the largest possible amount.
First establish what may realistically be available across suitable lenders. Then decide how much of that borrowing capacity you are actually comfortable using.
Why Two Lenders Can Give You Two Different Answers
Many borrowers assume lending is mathematical. Income goes in, expenses come out, and every bank should reach approximately the same answer.
In practice, lender policy matters enormously.
One lender may recognise a particular income source more favourably. Another may assess an existing commitment differently. A lender may calculate living expenses differently or have a different appetite for a particular borrower profile.
This is one reason going directly to your existing bank may not provide a complete picture.
Your bank may give you a perfectly accurate answer based on its own lending policy. But that doesn't necessarily tell you what another lender may be prepared to do.
The objective shouldn't be to find whichever lender will lend the absolute largest amount regardless of everything else. The objective is to understand the available options and select an appropriate lender and loan structure for your circumstances and objectives.
Don't Confuse Pre-Approval With A Spending Target
Another mistake we see is borrowers treating pre-approval like permission to spend every dollar available.
Imagine receiving pre-approval for a purchase price of $1.05 million. The natural temptation is to start searching from $950,000 to $1.05 million.
But pre-approval should define the outer boundary of what may be possible, not necessarily what should be spent.
There may be excellent properties at $900,000 that satisfy the buyer's needs while leaving substantially greater financial flexibility.
Property buyers can experience an unusual psychological effect. Once they know they can potentially afford $1 million, an $850,000 property may suddenly feel like a compromise even if it would have looked fantastic two weeks earlier.
The lending number can unintentionally become the property goal. Try to reverse that thinking. Start with the lifestyle and property requirements, then determine how much debt is necessary to achieve them.
Remember
Pre-approval is an indication of what may be available subject to lender conditions. It is not an instruction to spend to the maximum.
A Bigger Deposit Changes More Than Your LVR
Buyers often spend years concentrating on the deposit. That's understandable. Saving the deposit is one of the biggest hurdles when purchasing a home. But the deposit is only one side of the transaction. The other side is the debt that remains after settlement.
Consider two people purchase the same $1 million property.
Buyer A
$100,000 Deposit
$900,000 home loan
Buyer B
$200,000 Deposit
$800,000 home loan
The difference isn't simply that Buyer B contributed another $100,000 upfront. Their ongoing cash-flow position is also different.
Using our 6.15% example, the difference between the approximate repayments on the two loans is around $609 per month.
That is approximately $7,300 per year of cash-flow difference.
Over time, that can become significant.
This doesn't mean everyone should wait until they have a 20% deposit.
Waiting has consequences too, and there may be perfectly valid reasons to purchase earlier with a smaller deposit.
The important point is that:
Deposit strategy and repayment strategy should be considered together.
Don't focus exclusively on how much money is required to get into the property.
Also understand the debt you will be carrying after you get there.
The Buffer You Keep After Settlement Matters
There is another number that deserves attention:
How much money will you have left after you buy the property?
We sometimes see buyers become so focused on getting into a home that they consider putting almost every available dollar into the purchase.
That may reduce the loan amount, but it can also leave the household with very little liquidity after settlement.
Then life happens:
The hot-water system fails.
The car needs repairs.
Rates arrive.
Insurance is due.
A child becomes sick.
An unexpected trip is required.
Suddenly a household that owns a valuable property is relying on a credit card to meet a relatively small emergency.
That is why the best deposit strategy isn't automatically “put every dollar you have into the property.” The appropriate buffer varies between households. The important point is to think about it before settlement, not after the emergency occurs.
Borrowing Less Isn't Automatically Better
There is an important balance to all of this. We are not suggesting buyers should always purchase substantially below their borrowing capacity.
Being excessively conservative can have consequences too.
A family might purchase a smaller home to minimise its mortgage, only to outgrow the property two years later.
Selling and buying again can add another round of selling costs, legal costs, stamp duty, moving expenses, and other transaction costs.
Someone else might buy considerably further from work purely to reduce their loan amount, then discover that the additional commute materially affects their quality of life.
So the objective isn't:
“Borrow as little as possible.”
Nor is it:
“Borrow as much as possible.”
A better objective is:
Borrow an amount that allows you to purchase an appropriate property while preserving a level of financial flexibility you are comfortable with.
Sometimes that may mean using most of your available borrowing capacity.
Sometimes it may mean using considerably less.
The appropriate answer depends on the household and the property.
The objective is not:
“Borrow as little as possible.”
Nor is it:
“Borrow as much as possible.”
The goal is to borrow an amount that supports the right property while preserving an acceptable level of financial flexibility.
So, How Much Should You Actually Borrow?
There is no universal percentage or formula. Someone with a borrowing capacity of $900,000 may comfortably borrow the full amount. Another household with exactly the same borrowing capacity may decide $750,000 is their limit. Both decisions can be reasonable.
Before setting your property budget, consider the mortgage as part of your whole household position, not just as a lender calculation.
Look at:
- the expected mortgage repayment;
- what repayments could look like if interest rates were higher;
- council rates, strata where applicable, insurance and maintenance;
- your normal household and lifestyle expenses;
- how much cash you want available after settlement;
- your income stability;
- possible periods of reduced income;
- children, schooling and childcare;
- cars and transport;
- travel and other lifestyle priorities;
- whether you want to continue saving or investing; and
- the financial flexibility you want to preserve.
Then consider the property itself.
- Would buying substantially below your maximum still provide the type of home you need?
- Could you reasonably remain in that property for the period you expect?
- Would reducing the property budget create compromises elsewhere, such as location, commuting or the need to move again relatively soon?
The aim is to find the intersection between three things:
1. What a suitable lender may allow you to borrow
This establishes the financing possibilities.
2. What property appropriately meets your needs
This establishes what you are actually trying to purchase.
3. What level of repayment fits the life you want to maintain
This establishes your personal comfort level. When you consider those three questions together, borrowing capacity becomes useful information rather than a spending target.
A Practical Way to Set Your Property Budget
There is no universal percentage or formula.
Someone approved for $900,000 may comfortably borrow the full amount. Someone else with exactly the same borrowing capacity may decide that $750,000 is their limit.
Both decisions could be perfectly reasonable.
This is where good lending advice should move beyond simply obtaining the highest approval.
The Conversation Should Be
- What are you trying to achieve?
- What property do you actually need?
- What will the repayments look like?
- What happens if circumstances change?
- What financial flexibility would you like to preserve?
- Which lender's policy best fits your circumstances?
- How should the loan be structured around those objectives?
Once those questions are answered, you can work through the decision in the following order.
Step 1: You have established your realistic borrowing position
Understand what may be available based on your income, commitments and circumstances. Where appropriate, consider how suitable lenders may assess your position rather than relying entirely on a generic online calculator.
Step 2: Convert the loan into repayments
Don't think only in terms of a $700,000, $800,000 or $900,000 mortgage. Calculate what that debt means in monthly repayments.
Step 3: Add the costs of owning the property
Include relevant council rates, strata, insurance, maintenance and other ownership costs.
Step 4: Stress-test the household
Consider higher repayments and temporary reductions in income.
Ask what you would need to change if either occurred.
Step 5: Consider your next five years
Think about children, employment changes, travel, vehicles, investing and other major financial priorities.
Step 6: Decide what buffer you want after settlement
Don't determine your deposit without considering the amount of accessible cash you want to retain.
Step 7: Set your personal maximum
Only after working through those questions should the lender's maximum become your property-search range.
Your comfortable limit might equal your borrowing capacity.
It might not. The important thing is that the decision is deliberate.
The Bottom Line
Your borrowing capacity and your affordable mortgage are related, but they are not necessarily the same number.
Borrowing capacity tells you what may be possible under lender policy.
Your personal budget tells you what level of debt may be sustainable for the household and lifestyle you want.
A well-considered property budget takes both into account.
If you're thinking about buying a home, start by understanding your realistic borrowing position across appropriate lenders.
Then work backwards from the repayments, your future plans, the property you actually need and the financial flexibility you want to retain.
The goal isn't simply to get the biggest home loan approved.
It is to buy the right home with a mortgage you can comfortably live with.
One Final Thought
The goal isn't simply to get the biggest home loan approved.
The goal is to own a home without allowing the home loan to own your life.
About The Examples In This Article
The repayment examples in this article are illustrative only and use a 6.15% interest rate over a 30-year principal-and-interest loan term. Actual home loan rates, repayments, fees and borrowing capacity vary between lenders and borrowers.
The article also refers to APRA's mortgage serviceability buffer and Moneysmart guidance about considering the effect of higher interest rates when assessing mortgage affordability. Regulatory settings, lender policies and interest rates may change over time.
Always assess current lender policy and your individual financial position before making a property or borrowing decision.
General Information Disclaimer
This article contains general information only and does not take into account your objectives, financial situation or needs. Home loan eligibility, borrowing capacity and loan approval are subject to individual lender credit criteria, verification and assessment. Interest rates, lending policies and regulatory settings may change. Consider your circumstances and seek appropriate professional advice before making financial or property decisions.